Own a home in Britain. Never board a plane.
We arrange the mortgage, the solicitor, the bank account and the tenants for buyers who live outside the UK. One adviser, from the first call to the keys.
Advising since 2004 / Bangla, Urdu, Hindi and English
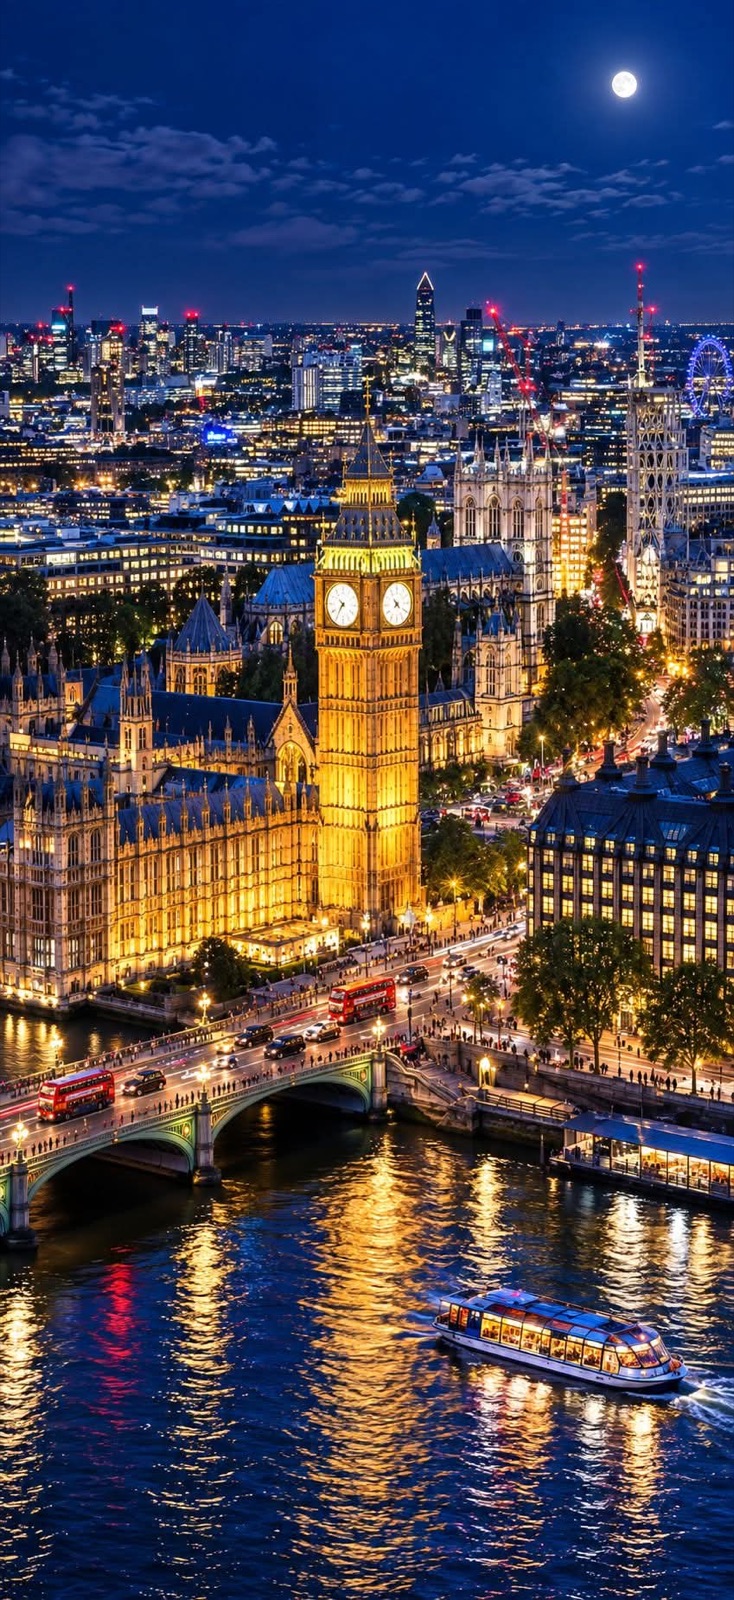
Property in the United Kingdom is held under one of the oldest and most predictable legal systems in the world. For buyers whose savings live in less certain places, a British address is a store of value, an income, and a door your family can always open.
- 25%
- Minimum deposit. We arrange finance for the remaining 75%.
- £25,000
- Minimum annual earned income, in any currency.
- 0
- Visits to the UK required. Everything is done by phone, email and WhatsApp.
Everything between you and the keys
Take the mortgage on its own, or hand us the whole purchase and the years of letting that follow.
Included with every mortgage
-
Mortgage arrangement
Finance up to 75% of the purchase price, sourced from lenders that accept overseas residents. How much you can borrow depends on the expected rent and your deposit.
-
A UK solicitor
We introduce a solicitor to complete the legal work and searches. Their fees are separate from ours.
-
A UK bank account
Your monthly payments are taken from a UK account. We guide you through opening one from abroad.
When you want more done for you
-
Property sourcing 0.5% of purchase price
Tell us the city, the budget and the yield you want. We shortlist, view and negotiate on your behalf.
-
Letting and management 15% of monthly rent
We find and vet tenants, collect the rent, handle repairs and send your income to you each month.
How a purchase unfolds
Our fee is paid in stages, only as each milestone is reached.
-
Consultation
We talk through your finances and goals. If you go ahead, you sign our terms of business, privacy notice, fee agreement and a letter of authority so we can speak to lenders for you.
£250 assessment fee, non-refundable
-
Fact find and property
We assess your income and outgoings. You send us the property you have chosen, or we find one for you.
-
Decision in principle
We choose the best lender for your circumstances and obtain a decision in principle, with an illustration showing your rate, monthly payment and term.
£2,500, first half of our fee
-
Application and valuation
We submit the full application. The lender's underwriters review it and instruct a surveyor to value the property.
-
Mortgage offer and legal work
The offer goes to you and your solicitor. Searches take around four to six weeks, then your solicitor asks you to transfer the deposit.
£2,500, second half of our fee
-
Completion
The lender releases the funds, your solicitor pays the seller's, and the keys go to you or your nominated agent. If you chose letting, we find your tenants from here.
When our fee is refunded
- If no mortgage offer is issued after the decision in principle, we refund £1,250.
- If completion does not happen after the offer, through no fault of yours, we refund £2,500.
- No refund is due if you change your mind after the offer, or if completion fails because facts were not disclosed.
- Our fee does not include solicitor, valuation or lender product fees. Stamp duty may apply; see gov.uk stamp duty rates.
See where you stand
Choose the country you live in and the price you have in mind. We'll show which of our lenders will consider you and what you need to have ready.
Enter your country to see which lenders will consider you.
- Aged 21 or over
- Not a politically exposed person
- A UK bank account for repayments
- Buy to let as standard; homes for you or close family where lenders allow
Shariah-compliant finance for residents of the Gulf
If you live in the United Arab Emirates, Saudi Arabia, Qatar, Kuwait, Bahrain or Oman, citizen or not, our partner bank offers Islamic finance through Commodity Murabaha, structured without interest.
The bank buys metal commodities and sells them to you for the finance amount plus an agreed profit, repaid in instalments over your chosen term. The bank arranges the trade on your behalf.
- Up to 75%
- Finance to value, for buy to let or a home you live in
- 2 or 5 years
- Fixed profit rate terms
- £100,000 to £5m
- Finance amount
- £150,000
- Minimum value outside inner London; £350,000 inside, for buy to let
- England and Wales
- New builds considered
- No UK credit history
- First-time buyers and first-time landlords welcome
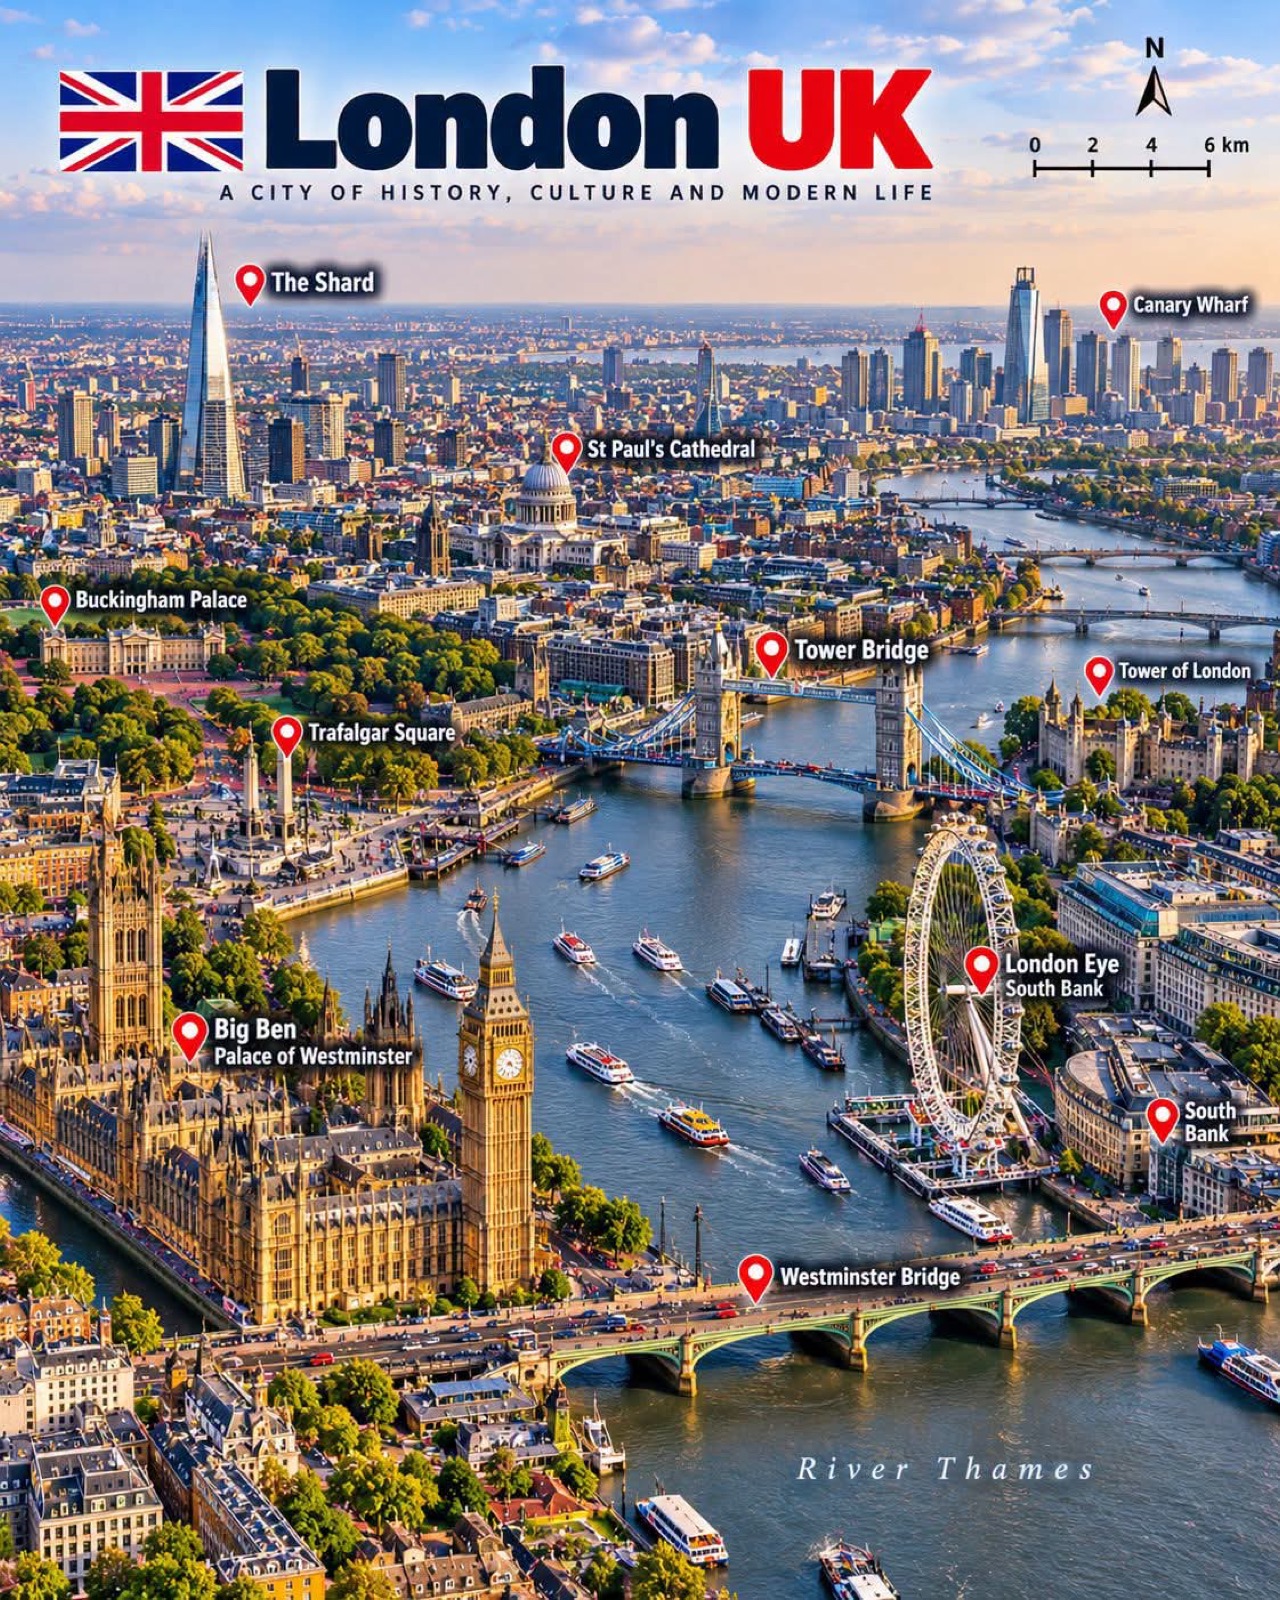
From the Thames to the Square Mile
London draws tenants from every corner of the world, and so do Birmingham, Manchester and the cities around them.
What to have ready
Send each document as a legible PDF by email. Anything not in English must be translated; we'll tell you which agencies your lender accepts.
Every applicant
- Valid passport
- Last three months' payslips, or 13 weeks if paid weekly
- Last three months' bank statements showing salary and outgoings
- A recent utility bill as proof of address
- Your most recent annual salary statement
- A bank statement proving your deposit and how it was saved
If you are self-employed or own 20% or more of a company
- Your last two years' accounts
- Your last two years' tax calculations from your home country's tax authority
- Your accountant's full details
- The date your business started, and ended if applicable
Additionally, for Islamic finance in the Gulf
- Six months' bank statements if you receive rental income
- A credit report from each country you have lived in over six years, dated within 30 days: AECB (UAE), SIMAH (Saudi Arabia), Ci-Net (Kuwait), Qatar Credit Bureau, Bahrain Portal
- Tenancy agreement if you rent your home, or title deeds if you own it
- Three months' credit card statements and annual statements for any mortgages
- School fee invoices, if you pay school fees
- For a limited company: three years' accounts, Companies House number and shareholdings
Opening a UK bank account from abroad
Online banks such as Wise, Revolut, Monzo and Starling, or the international divisions of HSBC, Barclays, NatWest, Lloyds, Santander and Skipton. We'll suggest the right one for your country.
One adviser, twenty years of lenders
Our founder and chief executive is a qualified financial adviser who has worked across UK banks, building societies and advisory networks since 2004.
That history is why lenders take our overseas cases seriously, and why we know which of them will say yes to yours. We speak Bangla, Urdu, Hindi and English, and you deal with the same person from first call to completion.
Speak to an adviser
Tell us a little about your plans. An adviser will reply in the language you prefer.
+44 7734 423470 (phone and WhatsApp)
Represent us in your country
We appoint self-employed representatives and introducers worldwide. Send your CV and a few words on how you would find clients to opportunity@buypropertyinuk.co.uk.